Buy 1c2.eu ?
We are moving the project
1c2.eu .
Are you interested in purchasing the domain
1c2.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy 1c2.eu ?
What is a payroll accounting?
Payroll accounting is the process of recording and managing a company's financial transactions related to employee compensation. This includes calculating and recording wages, salaries, bonuses, and deductions, as well as managing payroll taxes and other withholdings. Payroll accounting also involves ensuring compliance with labor laws and regulations, and providing accurate financial reports related to employee compensation. Overall, payroll accounting is essential for maintaining accurate and transparent financial records related to employee compensation within an organization. **
Does the inventory in accounting not match the target inventory?
If the inventory in accounting does not match the target inventory, it could indicate potential issues such as theft, errors in recording transactions, or discrepancies in the physical counting of inventory. It is important to investigate the root cause of the discrepancy and take corrective actions to reconcile the inventory. This may involve conducting a physical inventory count, reviewing transaction records, and implementing better inventory management practices to prevent future discrepancies. Regular monitoring and reconciliation of inventory can help ensure accurate accounting records and prevent potential losses. **

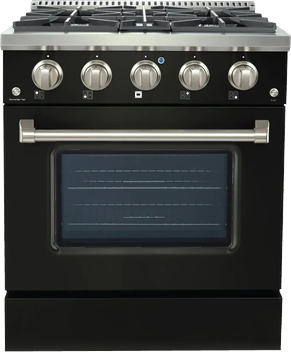
Similar search terms for Proline-PLSR-30-in
Top-Angebote
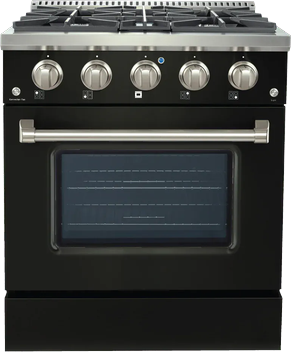
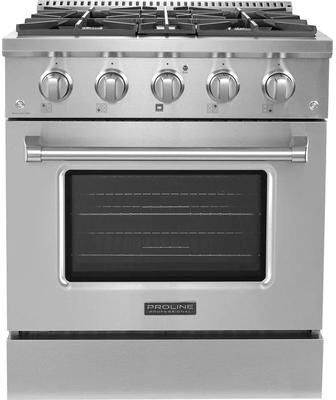
Products related to Proline-PLSR-30-in:


-
How is inventory valuation done in accounting?
Inventory valuation in accounting is done using different methods such as First-In-First-Out (FIFO), Last-In-First-Out (LIFO), and Weighted Average Cost. These methods determine the cost of goods sold and the value of ending inventory. FIFO assumes that the oldest inventory items are sold first, while LIFO assumes that the newest inventory items are sold first. Weighted Average Cost calculates the average cost of all units in inventory. The chosen method can have a significant impact on a company's financial statements and tax liabilities. **
-
How can I establish myself in payroll and financial accounting?
To establish yourself in payroll and financial accounting, it is important to first obtain relevant education and certifications such as a degree in accounting or finance, or a certification like Certified Payroll Professional (CPP) or Certified Public Accountant (CPA). Gain practical experience through internships or entry-level positions in payroll or accounting departments to develop your skills. Networking with professionals in the field, staying updated on industry trends, and continuously improving your knowledge through professional development opportunities will also help you establish yourself in the field. **
-
Should I take an accounting course or a payroll accounting course?
If you are interested in a broader understanding of accounting principles and practices, then taking an accounting course would be beneficial. However, if you are specifically interested in learning about the specialized area of payroll accounting, then a payroll accounting course would be more suitable. Consider your career goals and interests to determine which course would be the best fit for you. **
-
What are the accounting entries in the field of accounting for inventory valuation?
In the field of accounting, inventory valuation involves recording the cost of goods held for sale. The accounting entries for inventory valuation typically include debiting the inventory account to reflect the cost of goods purchased or produced, and crediting the corresponding account such as accounts payable or cash. Additionally, adjustments may be made to account for any changes in the value of inventory, such as writing down inventory to its lower of cost or market value. These adjustments are recorded by debiting cost of goods sold and crediting inventory reserve or loss account. **

What is a goal conflict in inventory management?
A goal conflict in inventory management occurs when different objectives or goals within the inventory management process are in conflict with each other. For example, the goal of minimizing holding costs by reducing inventory levels may conflict with the goal of ensuring high customer service levels by maintaining sufficient stock levels. This conflict can make it challenging for businesses to find the right balance between cost efficiency and customer satisfaction in their inventory management strategies. Resolving goal conflicts often requires careful planning, communication, and trade-offs to achieve a compromise that aligns with the overall objectives of the organization. **
What are the journal entries in accounting for inventory valuation?
The journal entries in accounting for inventory valuation typically involve recording the cost of inventory on the balance sheet. When inventory is purchased, the entry would debit the inventory account and credit the accounts payable or cash account. When inventory is sold, the cost of goods sold account is debited and the inventory account is credited for the cost of the items sold. Additionally, adjustments may be made to the inventory account to reflect changes in the value of inventory, such as write-downs for obsolete or damaged goods. **
Top-Angebote
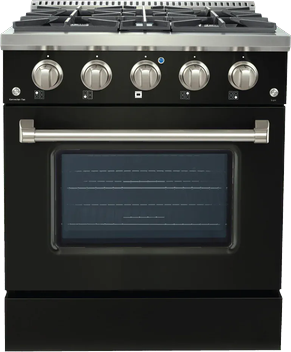
Products related to Proline-PLSR-30-in:
-
What is a payroll accounting?
Payroll accounting is the process of recording and managing a company's financial transactions related to employee compensation. This includes calculating and recording wages, salaries, bonuses, and deductions, as well as managing payroll taxes and other withholdings. Payroll accounting also involves ensuring compliance with labor laws and regulations, and providing accurate financial reports related to employee compensation. Overall, payroll accounting is essential for maintaining accurate and transparent financial records related to employee compensation within an organization. **
-
Does the inventory in accounting not match the target inventory?
If the inventory in accounting does not match the target inventory, it could indicate potential issues such as theft, errors in recording transactions, or discrepancies in the physical counting of inventory. It is important to investigate the root cause of the discrepancy and take corrective actions to reconcile the inventory. This may involve conducting a physical inventory count, reviewing transaction records, and implementing better inventory management practices to prevent future discrepancies. Regular monitoring and reconciliation of inventory can help ensure accurate accounting records and prevent potential losses. **
-
How is inventory valuation done in accounting?
Inventory valuation in accounting is done using different methods such as First-In-First-Out (FIFO), Last-In-First-Out (LIFO), and Weighted Average Cost. These methods determine the cost of goods sold and the value of ending inventory. FIFO assumes that the oldest inventory items are sold first, while LIFO assumes that the newest inventory items are sold first. Weighted Average Cost calculates the average cost of all units in inventory. The chosen method can have a significant impact on a company's financial statements and tax liabilities. **
-
How can I establish myself in payroll and financial accounting?
To establish yourself in payroll and financial accounting, it is important to first obtain relevant education and certifications such as a degree in accounting or finance, or a certification like Certified Payroll Professional (CPP) or Certified Public Accountant (CPA). Gain practical experience through internships or entry-level positions in payroll or accounting departments to develop your skills. Networking with professionals in the field, staying updated on industry trends, and continuously improving your knowledge through professional development opportunities will also help you establish yourself in the field. **
Similar search terms for Proline-PLSR-30-in
-
Proline PLSR 30 in. Gas & Dual Fuel Range — Matte Black Proline Range Hoods GasShop the Proline PLSR 30 in. Gas & Dual Fuel Range — Matte Black. Professional-grade gas & dual fuel range with powerful burners up to 20,000 BTU. Free shipping. Shop now!2599,99 $*Shipping: 0,00 $Secure redirect to the provider
-
Proline PLSR 30 in. Gas & Dual Fuel Range — Stainless Steel Proline Range Hoods GasShop the Proline PLSR 30 in. Gas & Dual Fuel Range — Stainless Steel. Professional-grade gas & dual fuel range with powerful burners up to 20,000 BTU. Free shipping. Shop now!2529,99 $*Shipping: 0,00 $Secure redirect to the provider
-
Should I take an accounting course or a payroll accounting course?
If you are interested in a broader understanding of accounting principles and practices, then taking an accounting course would be beneficial. However, if you are specifically interested in learning about the specialized area of payroll accounting, then a payroll accounting course would be more suitable. Consider your career goals and interests to determine which course would be the best fit for you. **
-
What are the accounting entries in the field of accounting for inventory valuation?
In the field of accounting, inventory valuation involves recording the cost of goods held for sale. The accounting entries for inventory valuation typically include debiting the inventory account to reflect the cost of goods purchased or produced, and crediting the corresponding account such as accounts payable or cash. Additionally, adjustments may be made to account for any changes in the value of inventory, such as writing down inventory to its lower of cost or market value. These adjustments are recorded by debiting cost of goods sold and crediting inventory reserve or loss account. **
-
What is a goal conflict in inventory management?
A goal conflict in inventory management occurs when different objectives or goals within the inventory management process are in conflict with each other. For example, the goal of minimizing holding costs by reducing inventory levels may conflict with the goal of ensuring high customer service levels by maintaining sufficient stock levels. This conflict can make it challenging for businesses to find the right balance between cost efficiency and customer satisfaction in their inventory management strategies. Resolving goal conflicts often requires careful planning, communication, and trade-offs to achieve a compromise that aligns with the overall objectives of the organization. **
-
What are the journal entries in accounting for inventory valuation?
The journal entries in accounting for inventory valuation typically involve recording the cost of inventory on the balance sheet. When inventory is purchased, the entry would debit the inventory account and credit the accounts payable or cash account. When inventory is sold, the cost of goods sold account is debited and the inventory account is credited for the cost of the items sold. Additionally, adjustments may be made to the inventory account to reflect changes in the value of inventory, such as write-downs for obsolete or damaged goods. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.